
Optimizing Roth Conversions in Boldin: Modeling a $3.6M DIY Retirement
By Zach Lundak | October 25, 2026
If you have spent decades stacking several million dollars for retirement, you probably already know that your biggest retirement challenge isn't saving—it's taxes.
For DIY retirees with $3 million, $4 million, or $5 million, a huge chunk of that wealth is usually locked up in tax-deferred accounts like traditional 401(k)s and IRAs. The problem? Down the road, when you begin taking required minimum distributions (RMDs) and turn on Social Security, you can easily get pushed into much higher tax brackets. There is a massive jump in the middle of the federal tax bracket range that catches people completely off guard.
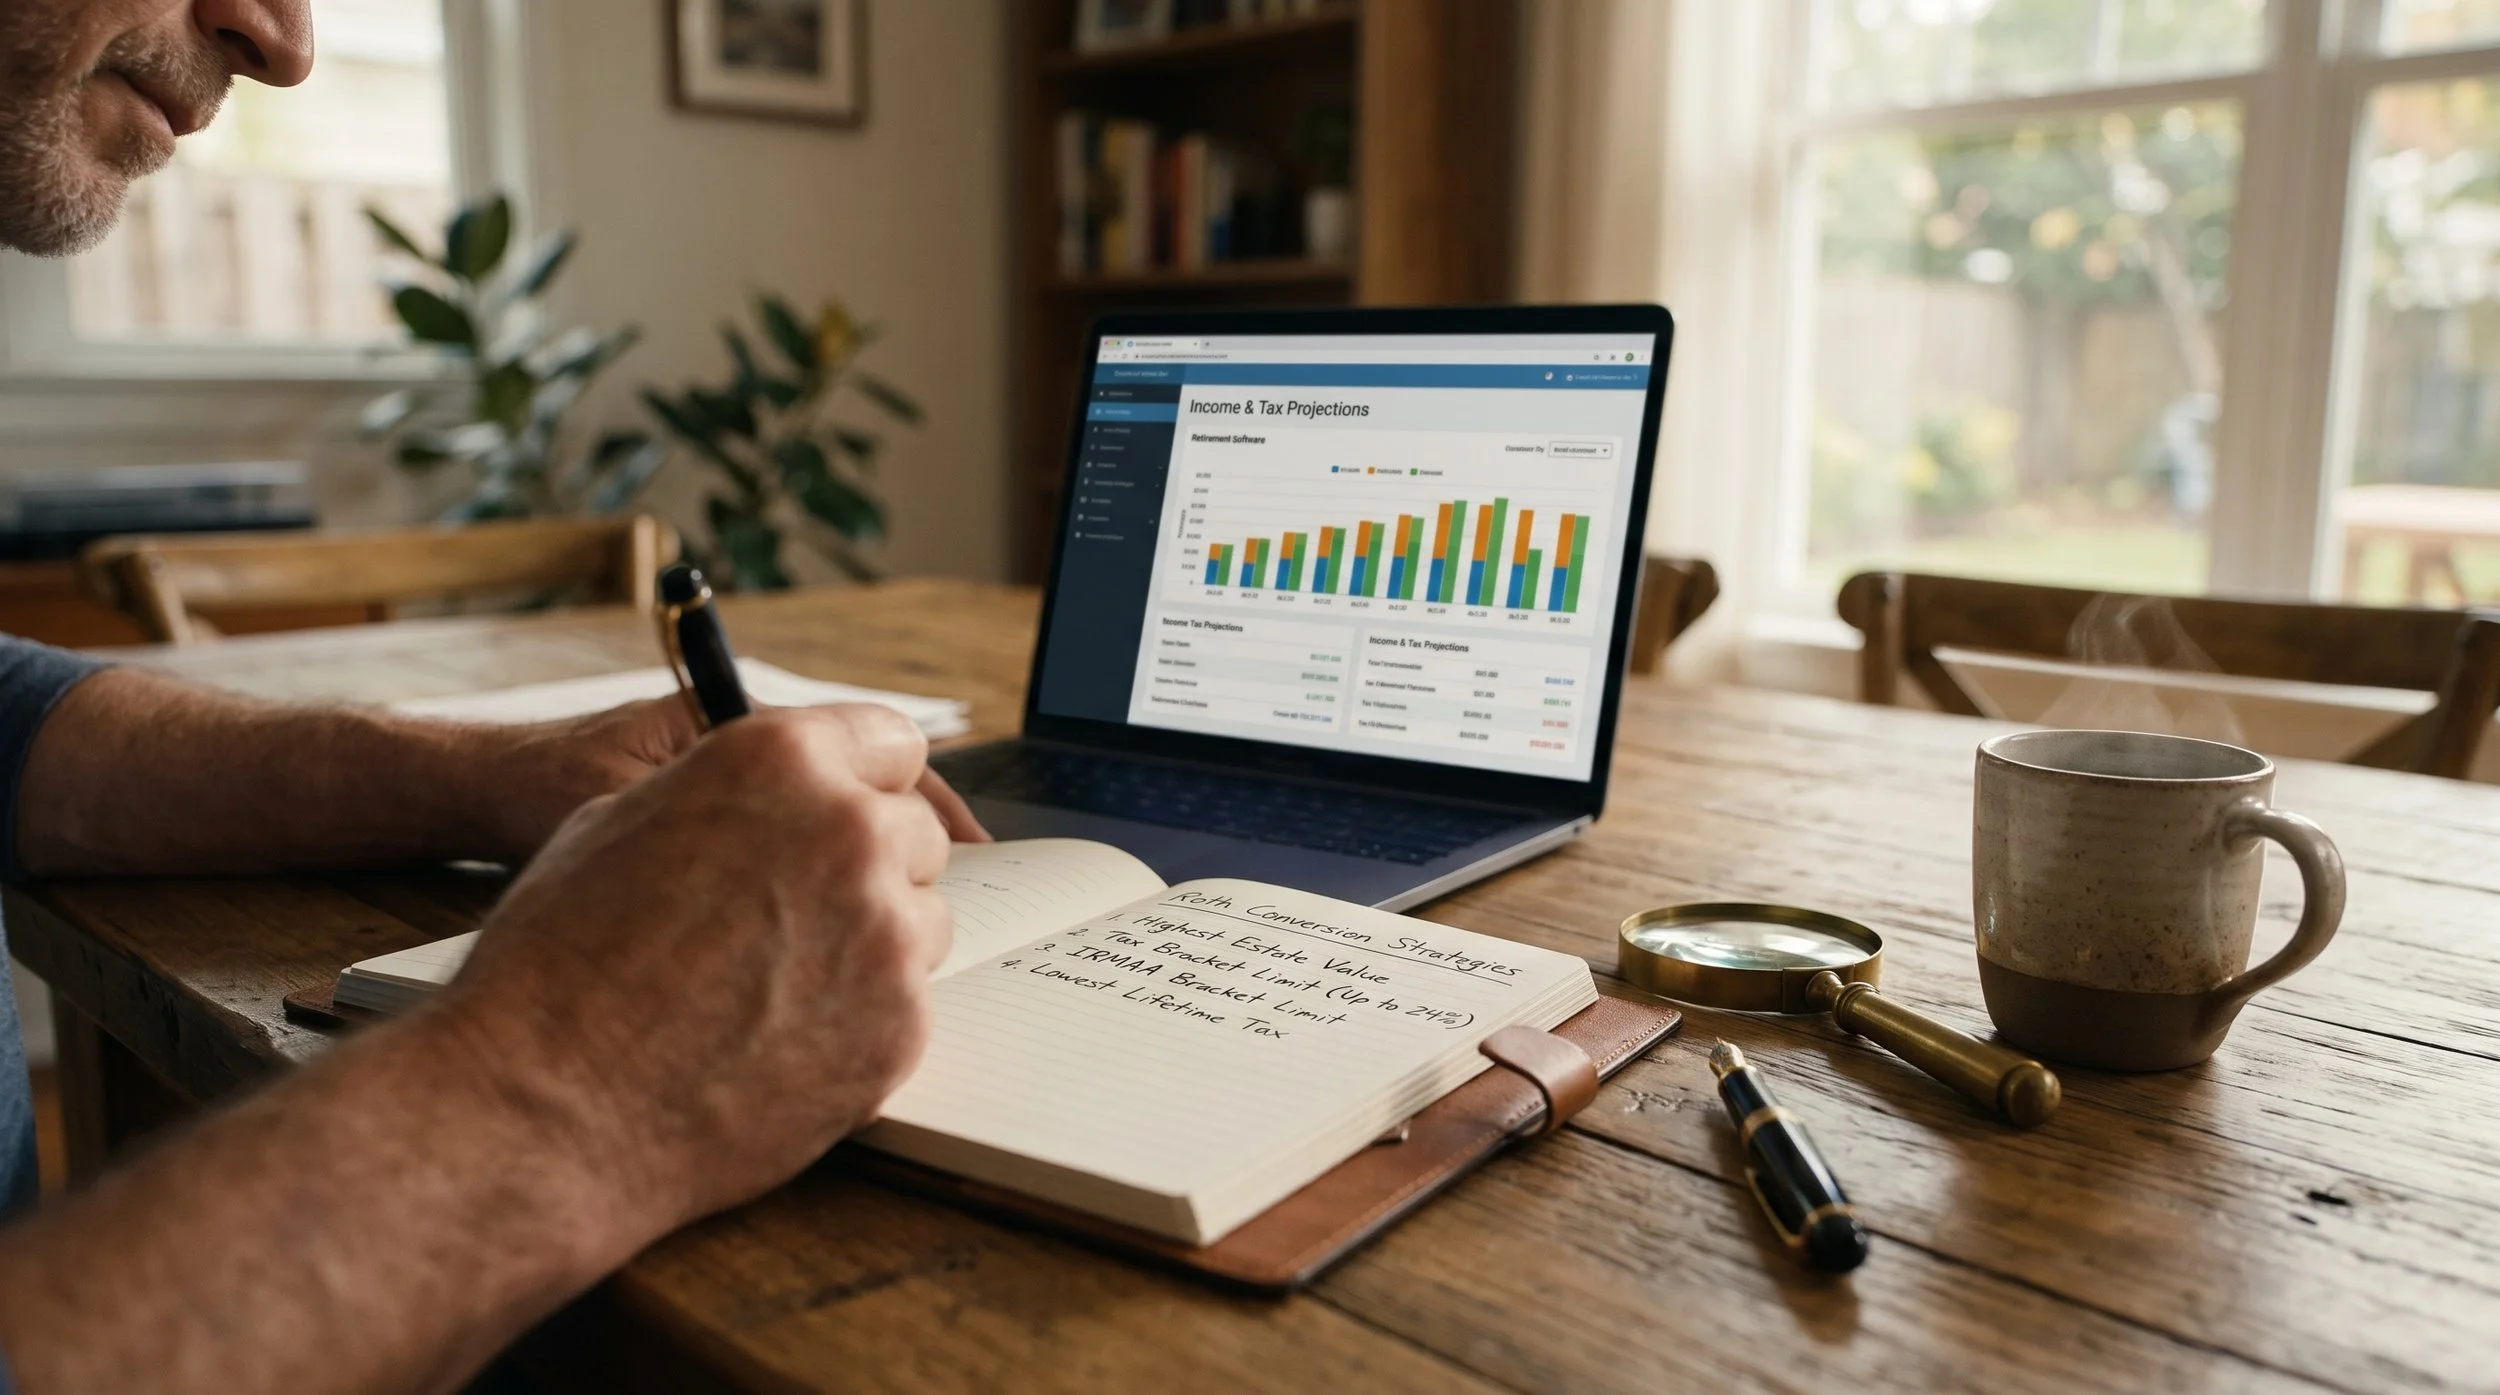
That is why modelling Roth conversions is one of the most critical steps in any retirement plan. Today, we are using Boldin (formerly NewRetirement) to show you exactly how the software allows you to model these conversions, and what each strategy means for your money.
The Base Case: An Agile $3.6 Million Plan
To see how Boldin handles these scenarios, here is the baseline profile we are modeling:
Age: 60 years old (targeting retirement in 2033 at age 67).
Household Background: Primary earner exiting a technology career; spouse is a retired educator.
Current Income: Earns roughly $10,000 per month.
Assets: $3.6 million, heavily concentrated in tax-deferred accounts, with small miscellaneous assets and home equity.
Retirement Income: A small pension is already being received, and Social Security is projected to start at Full Retirement Age (FRA).
When this transition occurs in 2033, this household will have immense income flexibility. The fixed pension is very small, and by delaying Social Security to age 70, they can create a massive "tax valley"—years with very little natural income. This is the golden window where you have the room to execute Roth conversions without pushing yourself into a sky-high bracket.
Importantly, right now, this portfolio has $0 in Roth accounts. Everything is starting from scratch.
Sizing Up Boldin’s 4 Roth Conversion Strategies
To start modeling, go to Boldin’s "Explorer" tab and find the Roth conversions module. The software allows you to view and test your plan through four distinct lenses, each based on a different financial priority:
1. Highest Estate Value
This strategy is all about leaving the absolute largest footprint of wealth behind, without obsessing over the deferred tax liabilities at the very end of your life expectancy.
Who it’s for: Ideal for individuals or families whose primary legacy goal is charitable giving.
Why it works: Because qualified charities do not pay income taxes on inherited tax-deferred accounts (like traditional IRAs), you don't need to aggressively convert everything to Roth. You can let the pre-tax accounts grow, knowing the tax liability will be completely wiped out when the assets are eventually donated.
2. Tax Bracket Limit
This is one of the most popular strategies for high-net-worth retirees who want to be highly surgical about their taxes year-to-year.
Who it’s for: DIYers who want to cap their tax bracket at a specific, sensible ceiling (like the 24% bracket).
Why it works: In the U.S. tax code, there is a steep, painful jump once you cross the 24% marginal bracket into the 32% and 35% tiers. This module lets you say: "Show me what happens if I convert just enough pre-tax money each year to fill up the 24% bracket, but not a single dollar more." It shows you the long-term compounding impact of systematically "chipping away" at your pre-tax burden at a controlled rate.
3. IRMAA Bracket Limit
A sibling to the tax bracket limit, this model focuses specifically on the "stealth tax" of Medicare Part B and Part D surcharges.
Who it’s for: Retirees who want to dodge Medicare surcharges or keep them capped at a pre-determined, comfortable level.
Why it works: IRMAA operates on strict "cliff" thresholds. If your income goes over a tier by even $1, your Medicare premiums spike. This module projects your future lifetime income and lets you limit your conversions to ensure your annual Modified Adjusted Gross Income (MAGI) never accidentally trips those expensive Medicare thresholds.
4. Lowest Lifetime Tax Liability
This option focuses entirely on minimizing the total, out-of-pocket tax payments you will personally make to the IRS during your lifetime.
Who it’s for: Retirees who want to pay the absolute least to the government while they are alive.
The Catch: While it optimizes your lifetime tax bill, it may not be the best choice for the wealth you leave behind. This model assumes that your heirs (like your children) might be in a lower tax bracket when they eventually inherit the money than you are right now, meaning it might make more sense to let them pay the tax later rather than you converting and paying it today.
Find the Right Lever for Your Legacy
There is no one-size-fits-all answer to Roth conversions. Whether your goal is minimizing your own lifetime taxes, capping your tax bracket, dodging Medicare IRMAA, or maximizing what you leave to charity, Boldin’s explorer lets you toggle these levers to see the visual, long-term impact on your nest egg.
At Barrett FP LLC, we provide hourly, advice-only financial planning. We don’t manage your assets or pitch you financial products—we give you the objective analysis and fiduciary guidance you need to model these strategies with 100% confidence.
Book an introductory retirement review: barrettplanning.com/start